Master complex family trust transfers with an Estate Tax Appraisal in Berkeley and Piedmont. Secure IRS-qualified, USPAP-compliant commercial asset valuations.

Navigating Multi-Asset Family Trust Transfers: Estate Tax Appraisal in Berkeley and Piedmont Commercial Portfolios

Managing multi-generational real estate portfolios across the East Bay requires balancing wealth preservation, legal structure, and strict tax compliance. In established communities like Piedmont and Berkeley, family trusts frequently hold diverse commercial and mixed-use real estate portfolios amassed over decades. When transferring these multi-asset holdings to heirs or settling an estate, securing an IRS-qualified Estate Tax Appraisal in Berkeley and Piedmont is a critical foundation for both federal compliance and long-term financial security.

Commercial real estate throughout Alameda County rarely fits into simple pricing models. From boutique storefronts along Solano Avenue to multi-tenant mixed-use developments along College and Telegraph Avenues, valuing complex real estate portfolios demands deep local expertise, rigorous income analysis, and an absolute commitment to federal standards.
The Valuation Issue: Commercial Complexity in Micro-Market Corridors

Establishing fair market value for commercial property within family trusts presents unique valuation hurdles that standard residential algorithms or national automated valuation models (AVMs) fail to capture. AVMs rely on high-level zip code averages and public records, completely overlooking micro-market lease dynamics, local tenant protections, physical deferred maintenance, and actual net operating income (NOI).

In East Bay commercial corridors, adjacent properties can carry radically different valuations based on intricate local variables:

  • Commercial Lease Structure and Tenant Terms: Long-term leases with below-market rents, master lease terms, or heavy tenant improvement (TI) allowances directly impact economic yield. Calculating the distinction between contract rent and market rent is fundamental when establishing true market value.

  • Mixed-Use Regulatory Restraints: Properties combining ground-floor commercial space with upper-level residential units in Berkeley are governed by municipal housing ordinances and local commercial zoning overlays, altering income projections and expense ratios.

  • Historical Preservation Constraints: Many commercial structures in Piedmont and Berkeley feature historic architectural elements. Navigating historic preservation guidelines, seismic retrofit mandates, and restricted development rights requires specialized appraisal methodologies.

Legal and Financial Implications: IRS Qualification and Basis Step-Up

When filing IRS Form 706 for estate tax purposes or establishing a step-up in basis under Treasury Regulation Section 1.1014-4, the IRS enforces stringent definitions for both the appraisal and the appraiser. Submitting a non-qualified appraisal or relying on informal broker opinions can trigger costly audits, substantial accuracy-related penalties under IRC Section 6662, and prolonged disputes among beneficiaries.

Retrospective Valuations and Date-of-Death Requirements

Estate tax returns often require a retrospective valuation established precisely as of the decedent’s date of death. In dynamic commercial real estate cycles, market conditions, capitalization rates, and prevailing interest rates on that specific historical date may differ markedly from present-day metrics. An independent appraiser must reconstruct historical market conditions using verifiable historical sales data, market cap rates, and lease archives to deliver an audit-defensible historical value.

Fractional Interest and Marketability Discounts

Multi-asset commercial portfolios in family trusts are frequently held through family limited partnerships (FLPs), LLCs, or tenancy-in-common (TIC) agreements. When transferring undivided partial interests to second- or third-generation heirs, calculating fractional interest discounts for lack of control and lack of marketability requires comprehensive market data and specialized financial analysis to survive IRS scrutiny.
The Pacific Appraisers Approach: Precision, Objectivity, and USPAP Compliance

At Pacific Appraisers, our approach to executing an Estate Tax Appraisal in Berkeley and Piedmont commercial portfolios rests on absolute independence, methodical local analysis, and full adherence to the Uniform Standards of Professional Appraisal Practice (USPAP).

1. Rigorous Income Capitalization and Cash Flow Audit

For commercial and mixed-use assets, we thoroughly analyze current rent rolls, operating expense statements, lease agreements, and local market vacancy trends. We apply both Direct Capitalization and Discounted Cash Flow (DCF) analyses tailored to East Bay cap rate expectations.

2. Comprehensive Micro-Market Sales Comparison

We evaluate comparable commercial transactions across specific East Bay corridors, applying precise adjustments for physical condition, location, density allowances, zoning restrictions, and lease terms.

3. IRS-Qualified and Defensible Reporting

Our certified commercial appraisers satisfy all IRS requirements for qualified appraisers under Treasury Regulations. Every report provides transparent methodology, fully documented market data, and verifiable logic designed to support estate planners, wealth managers, and CPAs during federal tax reviews.

Securing Your Multi-Asset Portfolio Strategy

Navigating complex family trust transfers and estate tax filings without an independent, professional appraisal exposes trustees and beneficiaries to unnecessary legal and financial risks. An objective valuation provides the clarity required to protect family wealth, ensure equitable distributions, and satisfy federal regulatory standards.

Need an audit-defensible commercial valuation for an estate, trust, or legal matter? Contact Pacific Appraisers today to schedule a confidential consultation. Our team delivers independent, expert valuation services across Santa Cruz, Monterey, and the entire Bay Area.
Beyond the Land: What Drives Agricultural Property Value in Monterey County?

Agricultural Property Appraisal Monterey County: Valuing Farmland, Water Rights, and Infrastructure

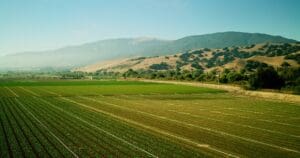
Monterey County is globally recognized as one of the most productive agricultural regions in the United States. Often referred to as the Salad Bowl of the World, the fertile soils of the Salinas Valley and surrounding coastal corridors produce high-value specialty crops ranging from leafy greens and berries to premium wine grapes. However, determining the true market value of agricultural real estate across this region requires far more than calculating basic acreage. A comprehensive agricultural property appraisal in Monterey County must account for intricate microclimates, complex water rights, soil quality classifications, and specialized physical infrastructure.

When farm owners, agricultural lenders, institutional investors, or family trusts require an accurate valuation, automated valuation models and generalized commercial appraisals fall short. Valuing agricultural holdings requires deep local market intelligence, strict adherence to professional appraisal standards, and an objective analysis of property-specific utility.

The Complex Realities of Monterey County Farmland Valuations

Evaluating agricultural land throughout Monterey County involves analyzing variables that are entirely unique to Central Coast farming. Unlike Midwestern row-crop acreage or uniform real estate developments, every agricultural parcel between the Santa Lucia Range and the Gabilan Mountains carries distinct physical and legal characteristics.

Soil Classification and Microclimates

The soil composition directly dictates crop yield, crop rotation possibilities, and long-term land capability. Prime farmland featuring Class I and Class II alluvial soils commands a significant premium over lower-tier ground. Furthermore, coastal proximity introduces specific microclimates. Northern valley parcels closer to Monterey Bay benefit from marine fog and cooler temperatures ideal for cool-season vegetables like lettuce, broccoli, and celery, as well as berries. Heading south toward King City and Greenfield, higher heat units shift the land utility toward wine grapes, tomatoes, and forage crops. An appraiser must measure how these physical limitations influence the land’s highest and best use.

Groundwater Availability and Water Rights

Water security is arguably the most critical component of agricultural value in California. In Monterey County, agricultural operations rely heavily on groundwater basins managed under the Sustainable Groundwater Management Act (SGMA). An appraisal must evaluate:

  • Groundwater quality, including salinity levels and potential seawater intrusion risks in coastal zones.

  • Pumping capacity and well infrastructure reliability.

  • Adjudicated water rights, allocation limits, and compliance costs under local Groundwater Sustainability Agencies (GSAs).

  • Historical water usage records and irrigation efficiency.

A parcel with abundant, high-quality groundwater and updated pumping infrastructure maintains a fundamentally different asset value than neighboring land facing pumping restrictions or deteriorating water quality.

Specialized Agricultural Infrastructure

Valuing agricultural real estate extends beyond the dirt. On-site improvements and specialized structures significantly impact property utility and income capability:

  • High-capacity irrigation systems, underground mainline piping, and automated filtration plants.

  • Coolers, cold storage facilities, and packing sheds that support post-harvest processing.

  • Worker housing facilities, equipment barns, and staging yards.

  • Permanent crop installations, such as trellised vineyards or berry hoop houses, which require distinct capitalization analyses.

Legal and Financial Implications for Property Owners

Agricultural property owners throughout Monterey County require precise appraisals across a range of legal, financial, and strategic scenarios.

Financing and Commercial Lending

Agricultural lenders require objective, USPAP-compliant valuations before underwriting land acquisitions, infrastructure expansion loans, or operating lines of credit. Because agricultural values fluctuate based on crop economics and environmental factors, lenders rely on defensible valuations that accurately reflect land productivity rather than speculative trends.

Estate Planning, Trust Administration, and Tax Compliance

Family-owned farming operations represent multi-generational assets. Establishing an accurate baseline value is essential when executing estate plans, navigating gift tax reporting, or settling date-of-death valuations. Furthermore, many agricultural properties in Monterey County are enrolled in Williamson Act (Land Conservation Act) contracts, which restrict land use in exchange for property tax assessments based on agricultural income rather than market value. Valuing restricted land for estate or tax purposes requires specialized valuation techniques.

Partnership Dissolutions and Land Division

When agricultural partnerships dissolve or family co-owners seek a buyout, establishing an unbiased valuation prevents prolonged disputes. Appraisers must evaluate partial interests, leasehold structures, and tenant-farmer lease agreements to deliver a clear financial benchmark for all parties involved.

The Local Appraiser Approach to Agricultural Valuations

Delivering a court-defensible and bank-grade valuation requires an appraiser who understands the local agricultural ecosystem. At Pacific Appraisers, our approach combines rigorous methodology with on-the-ground local expertise.

Application of Appraisal Methodologies

In accordance with the Uniform Standards of Professional Appraisal Practice (USPAP), an agricultural appraisal synthesizes three primary approaches to value:

  1. Sales Comparison Approach: Comparing the subject property to recent sales of similar agricultural acreage in Monterey County. Adjustments are carefully quantified for soil capability, water access, parcel size, location, and Williamson Act status.

  2. Income Capitalization Approach: Converting the net operating income generated by crop production or cash-lease agreements into an indication of capital value. This approach analyzes local cash rents, crop-share agreements, and typical landlord expenses across the Salinas Valley.

  3. Cost Approach: Evaluating the replacement cost of physical improvements, such as wells, irrigation networks, and packing structures, adjusted for physical depreciation and functional obsolescence.

Beyond Automated Data

Generic valuation algorithms and distant appraisers often fail to account for hyper-local nuances. An automated model cannot read a well test report, evaluate the impact of a local GSA pumping limit, or differentiate between prime vegetable ground and ground constrained by drainage issues. Independent, on-site inspections combined with verification of public records, water basin data, and agricultural lease trends ensure that every report stands up to scrutiny from financial institutions, legal counsel, and tax authorities.

Whether managing a multi-generational row-crop ranch in the Salinas Valley, a vineyard in the Arroyo Seco AVA, or coastal farmland near Watsonville and Pajaro Valley, an accurate valuation serves as the foundation for sound financial decision-making.

Request an Agricultural Property Appraisal

Pacific Appraisers delivers independent, high-authority valuation services across Monterey County, Santa Cruz County, and the greater San Francisco Bay Area. To discuss your agricultural property, commercial asset, or private estate valuation needs with an expert appraiser, contact our team today for a confidential consultation.

Discover why objective, USPAP-compliant commercial appraisals in Silicon Valley are essential for accurate R&D and industrial property valuations in San Jose.

Commercial Valuation in San Jose: Navigating R&D and Industrial Asset Complexity

Silicon Valley remains a global focal point for innovation, driven by advanced hardware engineering, biotechnology, and specialized manufacturing. At the core of this economic engine lies the San Jose industrial and R&D property market. Valuing these highly specialized commercial assets requires a level of analytical precision that standard Automated Valuation Models (AVMs) and broad regional appraisals simply cannot deliver.

From modern flex-industrial spaces along the Montague Expressway to high-density R&D campuses in North San Jose, commercial property performance in Santa Clara County is shaped by intricate lease structures, tenant improvement capitalization, and technical building infrastructure. Whether preparing for an acquisition, balance sheet restructuring, or partnership buyout, institutional investors and property owners need a rigorous, defensible valuation approach grounded in local market realities.

The Unique Realities of Silicon Valley Industrial Real Estate

San Jose industrial and flex properties differ significantly from standard warehouse or distribution assets. R&D buildings frequently feature specialized buildouts, including cleanrooms, heavy three-phase power upgrades, specialized HVAC and gas delivery systems, and elevated ceiling heights.

Determining the market value of these improvements presents a unique challenge:

  • Tenant Improvement (TI) Depreciation vs. Residual Value: High-cost specialized buildouts tailored to a specific tech or biotech tenant may hold significant value for a similar occupant, but could represent a removal liability for a traditional user.

  • Adaptive Reuse Potential: Assessing whether an aging Class B industrial building can be converted into flex space or data-adjacent infrastructure requires deep knowledge of local zoning overlay districts and power grid capacity.

  • Income Capitalization Nuances: Capitalization rates for Silicon Valley industrial assets vary widely based on tenant creditworthiness, lease duration (triple net vs. modified gross), and built-in rent escalation clauses.

Relying on generic capitalization rates or algorithmic estimates creates substantial exposure to financial and legal risk. An accurate evaluation demands a granular examination of net operating income (NOI), expense recovery structures, and local absorption trends.

Financial and Legal Implications of Commercial Appraisal Accuracy

For corporate leaders, private equity funds, and commercial property owners, a property valuation serves as the foundational benchmark for major financial transactions. Miscalculating the fair market value of an R&D facility in San Jose can trigger significant collateral consequences:

  1. Lending and Capital Allocation: Commercial lenders enforce strict Debt Service Coverage Ratio (DSCR) and Loan-to-Value (LTV) limits. An inaccurate valuation can complicate loan underwriting or result in unfavorable borrowing terms.

  2. Partnership Buyouts and Tax Strategy: In partnership dissolutions or corporate restructuring, an unsupported asset valuation opens the door to litigation among stakeholders or challenges from tax authorities.

  3. Property Tax Appeals: With changing market conditions, property owners may overpay property taxes if the assessed value fails to reflect shifts in local vacancy rates or functional obsolescence.

Achieving court-defensible and audit-ready results requires strict adherence to the Uniform Standards of Professional Appraisal Practice (USPAP). USPAP compliance ensures that every assumption, market comparable, and financial projection is independently verified and methodologically sound.

The Local Appraiser Advantage: Going Beyond the Algorithm

Commercial real estate in Santa Clara County cannot be evaluated using macro-level statistics alone. Algorithms and out-of-market valuation providers often fail to account for hyper-local micro-markets. Factors such as proximity to light rail corridors, specific San Jose submarket zoning restrictions, and tenant-specific lease terms directly impact property value.

An experienced local valuation expert applies three core approaches:

  • Income Capitalization Approach: Analyzing historical operating statements, verifying expense pass-throughs, and applying market-derived cap rates or discounted cash flow (DCF) models based on local lease transactions.

  • Sales Comparison Approach: Adjusting truly comparable industrial and R&D property sales based on square footage, power capacity, clear height, office-to-lab ratio, and location advantages.

  • Cost Approach: Evaluating the replacement cost of specialized building infrastructure while accounting for physical deterioration, functional obsolescence, and external market factors.

By synthesizing these methodologies, an independent appraiser delivers an objective, highly defensible valuation report that stands up to scrutiny from financial institutions, auditors, and courts.

Partner with Regional Valuation Authorities

Navigating the complexities of commercial real estate in Northern California demands localized expertise, technical skill, and uncompromising independence. Whether you require an appraisal for an R&D facility in San Jose, an agricultural land holding in Monterey County, or a multi-family asset in San Francisco, Pacific Appraisers provides authoritative valuation solutions tailored to your requirements.

Contact Pacific Appraisers today to request a confidential consultation for your commercial, institutional, or private client property needs across Santa Cruz, Monterey, and the greater San Francisco Bay Area.

Navigating university real estate valuation in San Francisco?

Navigating University Real Estate Valuation in San Francisco: A Guide to Institutional Land and Ground Lease Appraisals

Institutional real estate within urban higher education corridors demands an appraisal approach that goes far beyond standard commercial techniques. In dense metropolitan nodes like San Francisco, public and private universities, medical centers, and institutional investment boards frequently execute complex property transactions. These range from long-term Public-Private Partnerships (P3) and master-plan ground leases to campus edge acquisitions for research and development space.

Whether a university endowment board is assessing an off-campus portfolio or a commercial lender is underwriting a private developer’s ground leasehold mortgage, establishing precise market value requires localized expertise. Automated Valuation Models (AVMs) and regional non-specialist appraisers often fall short when confronted with San Francisco’s unique regulatory environment, tax-exempt institutional overlays, and long-term land lease structures.

The Core Valuation Challenges in University Real Estate

Higher education institutions in San Francisco operate in one of the most supply-constrained real estate markets in North America. Valuing institutional assets or commercial real estate tied to university operations introduces distinct complexities that require specialized analysis.

1. Ground Lease and Split-Interest Valuations

Many university-adjacent developments, such as innovation districts, student housing complexes, or medical office buildings, are structured on ground leases lasting 50 to 99 years.

Valuing these transactions requires isolating two distinct legal positions:

  • The Leased Fee Interest: The university’s underlying ownership of the land, which yields contract ground rent and holds the reversionary interest once the lease expires.

  • The Leasehold Interest: The private developer or operator’s right to improve, manage, and collect cash flows from the building during the lease term.

Accurately appraising these split interests demands rigorous Discounted Cash Flow (DCF) modeling. Appraisers must evaluate complex lease provisions, including periodic rent reset mechanisms (often tied to Consumer Price Index metrics or fair market land value reappraisals), subordination clauses, and casualty loss terms.

2. Highest and Best Use (HBU) in Institutional Contexts

A fundamental requirement of Uniform Standards of Professional Appraisal Practice (USPAP) compliance is determining the property’s Highest and Best Use: the use that is physically possible, legally permissible, financially feasible, and maximally productive.

When a university acquires commercial parcels along the campus periphery, the current use (e.g., an older low-rise office building or neighborhood retail strip) may not represent its highest and best use. The valuation must account for:

  • Zoning and Municipal Entitlements: Local San Francisco planning codes, density bonuses, and institutional master plan designations.

  • Assemblage Potential: The incremental value created by combining adjacent parcels to support larger campus facilities or housing.

  • Alternative Commercial Uses: Evaluating whether private commercial operation or institutional repositioning yields the highest market value.

3. Public-Private Partnerships (P3) and Private Capital Risk

To fund new student housing, life science laboratories, and incubator spaces without expanding debt burdens, institutions increasingly rely on P3 structures. Lenders financing these P3 developments need defensible appraisals to underwrite leasehold mortgages.

An appraisal for a P3 project must stress-test revenue projections against academic calendar occupancy, university master lease guarantees, and shifting cap rates in the broader San Francisco commercial real estate market.

Structural Comparison: University Ground Lease Interests

Understanding the division of rights and valuation mechanics between land owners and site developers is essential for institutional risk management.

Property Interest Primary Asset Holder Valuation Basis & Methodologies Critical Appraisal Risk Variables
Leased Fee Interest (Fee Simple Land) University or Institution Yield capitalization of ground lease rent streams + discounted value of ultimate property reversion. Inadequate rent reset formulas; credit risk of tenant; long-term discount rate selection.
Leasehold Interest (Improvements & Operating Rights) Private Developer / Investor / Lender Discounted Cash Flow (DCF) of net operating income generated by improvements over remaining lease term. Ground lease expiration timing; lease reset shocks; debt service coverage limits.

Legal and Financial Implications of Institutional Appraisals

Commercial real estate appraisals for university assets or lender financing on institutional ground leases serve critical governance and financial functions:

  • GAAP and Financial Reporting Compliance: Universities, non-profit foundations, and endowment funds require periodic fair market value appraisals to satisfy Generally Accepted Accounting Principles (GAAP) and Governmental Accounting Standards Board (GASB) standards for balance sheet reporting.

  • Lender Underwriting and Regulatory Oversight: Commercial banks and institutional lenders financing campus-edge commercial assets or ground-lease developments must comply with federal regulations (including 12 CFR Part 34 and Interagency Appraisal and Evaluation Guidelines). A USPAP-compliant appraisal ensures loan-to-value (LTV) and debt service coverage ratio (DSCR) calculations rest on verified market data.

  • Fiduciary Responsibility in Property Transactions: When an institution buys, sells, or leases real estate, university trustees and board members hold a fiduciary duty to transact at fair market value. An independent appraisal protects leadership from public scrutiny or regulatory challenge.

The Local Appraiser Approach: Precision in the San Francisco Market

Navigating San Francisco’s real estate landscape demands seasoned local judgment. A generic appraisal model cannot capture the micro-market dynamics of neighborhoods like Mission Bay, the Presidio, or South of Market.

At Pacific Appraisers, our commercial valuation methodology for institutional and university real estate includes:

  1. Granular Ground Rent & Land Sale Analyses: We analyze local land sales, entitlement costs, and prevailing ground rent yields across San Francisco and the broader Bay Area to establish defensible baseline land values.

  2. Custom Discounted Cash Flow (DCF) Modeling: We build customized DCF models that reflect exact ground lease terms, contractual rent escalations, terminal cap rate sensitivity, and institutional vacancy patterns.

  3. Rigorous USPAP Compliance & Independent Analysis: Every valuation report undergoes structured internal review to ensure absolute independence, defensibility, and compliance with institutional standards.

Request a Confidential Commercial Valuation Consultation

Navigating university land transactions, ground lease structuring, or campus-edge commercial lending requires clear market data and credible valuation reports. Pacific Appraisers provides USPAP-compliant commercial appraisal and strategic advisory services across Santa Cruz, Monterey, and the San Francisco Bay Area.

Contact our commercial valuation team today to discuss your project requirements or request an appraisal quote:

  • Direct Commercial Line: (831) 607-3800

  • Email: Orders@PacificAppraisers.com

  • Corporate Head Office: 9010 Soquel Drive, Suite 3, Aptos, CA 95003

“Why are luxury coastal homes in Carmel so hard to value before making an offer?”

Pre-Purchase Luxury Appraisal Carmel: Valuing Carmel-by-the-Sea Real Estate Before You Offer

Buying a high-end estate in Carmel-by-the-Sea is unlike purchasing residential property anywhere else in California. Known for its coastline, architectural character, and strict local building ordinances, Carmel commands some of the highest price-per-square-foot valuations in the country. However, the factors that make Carmel homes so desirable also make them exceptionally difficult to price accurately.

When preparing to submit a non-contingent offer on a multi-million-dollar coastal home, relying on automated valuation models or generic market estimates introduces significant financial risk. A pre-purchase luxury appraisal tailored to Carmel provides the independent clarity high-net-worth buyers and their advisors need to make confident, well-supported decisions.

Why Standard Automated Valuations Fail in Coastal Carmel

In standardized suburban developments, Automated Valuation Models (AVMs) and standard algorithms rely heavily on recent sale prices of nearby homes with similar square footage and bedroom counts. In Carmel, this approach collapses.

Carmel real estate is defined by extreme property heterogeneity. Two properties situated on the same block can vary in market value by millions of dollars due to factors that algorithms cannot process:

  • View Corridors: A unobstructed ocean view, a filtered view through Monterey pines, or a view vulnerable to future tree growth command radically different valuation adjustments.

  • Microclimates and Sun Exposure: Proximity to the fog line and lot orientation heavily influence daily light, dampness, and overall liveability.

  • Architectural Prominence: Historical significance, custom stone or timber craftsmanship, and famous architectural provenance create unique premium adjustments that require professional appraisal judgment.

  • Lot Topography: Blufftop parcels carry steep geological sensitivities and coastal commission rules that Canyon or inland lots do not face.

When algorithm-driven tools attempt to evaluate Carmel-by-the-Sea or the nearby Carmel Highlands, they fail to capture these non-standard variables. The result is often either an inflated valuation that leads to overpaying or an underestimation that causes a competitive buyer to lose a prized property.

The Valuation Mechanics of Non-Conforming Luxury Estates

A primary challenge when establishing a fair market value in Carmel is navigating non-conforming structures and land-use restrictions. Many historic cottages and custom estates were built prior to modern municipal zoning regulations. As a result, properties frequently feature unique footprints, setbacks, or building heights that could not be replicated under current local codes.

Strict Municipal and Coastal Guidelines

Carmel-by-the-Sea maintains rigorous urban planning guidelines designed to preserve its forested, village-like character. The Monterey County Coastal Implementation Plan and local municipal codes enforce strict floor-area ratios, site coverage limits, and tree removal restrictions.

When evaluating a luxury property for pre-purchase consulting, a certified appraiser must determine the property’s Highest and Best Use. This analysis considers four critical criteria:

  1. Legally Permitted: Analyzing existing non-conforming rights versus current rebuilding limitations.

  2. Physically Possible: Assessing lot coverage, steep slopes, drainage, and soil stability.

  3. Financially Feasible: Determining if prospective renovations or additions add market value proportional to their cost.

  4. Maximally Productive: Identifying the specific property configuration that yields the highest market value.

Understanding whether a home can be expanded or if a non-conforming element can be rebuilt after a casualty event is essential to determining its true economic value prior to close of escrow.

Legal and Financial Implications for High-Net-Worth Buyers

For private clients, family offices, and wealth managers, an objective pre-purchase valuation serves as a key risk-management tool. Unbiased appraisal reports deliver distinct strategic advantages during high-stakes negotiations:

+-----------------------------------------------------------------------------------+
|                        PRE-PURCHASE APPRAISAL ADVANTAGES                          |
+------------------------------------------------------+----------------------------+
| Risk Factor                                          | Pre-Purchase Solution      |
+------------------------------------------------------+----------------------------+
| Overpaying due to emotional bidding wars             | Independent market floor   |
| Mortgage underwriting gaps on non-conforming homes   | Early appraisal insight    |
| Capital allocation errors across trust portfolios    | Fully supported USPAP data |
+------------------------------------------------------+----------------------------+

Navigating Non-Contingent Offers

In competitive coastal markets, buyers often choose to waive appraisal contingencies to make their offers more attractive to sellers. Executing a non-contingent contract without an independent pre-purchase valuation exposes the buyer to potential appraisal shortfalls during lender underwriting, requiring unexpected cash outlays at closing.

Protecting Trust and Fiduciary Assets

When luxury real estate is acquired through a family trust, limited liability company (LLC), or private partnership, trustees have a fiduciary obligation to verify that capital is deployed at fair market value. A comprehensive valuation report provides a documented, defensible audit trail that satisfies trust beneficiaries, advisors, and auditors.

The Pacific Appraisers Approach to Carmel Luxury Real Estate

At Pacific Appraisers, our valuation methodology combines local geographic expertise with strict adherence to the Uniform Standards of Professional Appraisal Practice (USPAP). We do not rely on high-level averages or automated metrics. Instead, we execute a meticulous evaluation process tailored to coastal environments:

  1. Hyper-Local Micro-Market Analysis: We evaluate micro-neighborhood trends, isolating pricing variables between Golden Rectangle locations, Point Lobos view corridors, and hillside Carmel Highlands parcels.

  2. Qualitative Comparable Selection: We select comparable sales based on architectural tier, construction quality, view orientation, and effective age rather than simple geographical proximity.

  3. Detailed On-Site Inspection: Our appraisers examine the physical quality of finishes, floor plan functionality, non-conforming outbuildings, guest units, and overall site utility.

  4. Unbiased Independence: Pacific Appraisers operates purely as an independent third-party valuation firm. We hold no stake in the outcome of the transaction, ensuring our conclusions are entirely objective, impartial, and balanced.

By isolating true land value from structural improvements and adjusting for specific view rights, we deliver clear, defensible valuations that allow luxury buyers to negotiate with complete confidence.

Navigating the unique nuances of Carmel-by-the-Sea real estate requires localized expertise and proven appraisal methodology. Whether you are acquiring a historic coastal cottage, an oceanfront estate, or an architectural sanctuary, securing an independent pre-purchase appraisal protects your capital and validates your investment strategy.

Pacific Appraisers provides USPAP-compliant valuation and real estate consulting services across Monterey County, Santa Cruz County, and the broader San Francisco Bay Area. Contact our team today for a confidential consultation regarding your upcoming luxury property acquisition.

Examining the Role of Ethics and Professional Standards in Appraiser Exams in California Commercial Real Estate

Ethical Foundations in California Commercial Real Estate Appraisal

A commercial real estate appraiser carefully examining a property, surrounded by professional standards and ethical guidelines

In California, ethical practice is vital for commercial real estate appraisers. Key elements include strict adherence to established professional standards and a focused effort on reducing bias.

Uniform Standards of Professional Appraisal Practice (USPAP) Compliance

The Uniform Standards of Professional Appraisal Practice (USPAP) serve as the guiding framework for ethical appraisal. We ensure appraisers maintain objectivity through regular training. USPAP sets essential guidelines, influencing every step of the appraisal process. Adhering to USPAP helps us avoid conflicts of interest and maintain transparency. Compliance is not just recommended; it’s required by the Bureau of Real Estate Appraisers to uphold integrity. We stay updated with current USPAP revisions, providing appraisers with clear expectations.

Code of Ethics and Professional Responsibility

Our Code of Ethics and Professional Responsibility highlights integrity and professionalism. We emphasize honesty and diligence across all assignments. This code supports fair practices in the California commercial real estate sector, adapting as necessary to meet emerging challenges. We hold appraisers accountable to these standards, reflecting our commitment to ethical behavior. As part of this ethical framework, appraisers must consistently demonstrate a commitment to accuracy, objectivity, and reliability in their work.

Enforcement and Handling of Complaints

Enforcement plays a crucial role in maintaining ethical standards. We have established processes to handle complaints promptly and efficiently, protecting both the public and the appraisal community. The Bureau of Real Estate Appraisers investigates alleged violations, ensuring accountability. Transparent procedures help us address concerns and uphold trust in the industry. By prioritizing integrity, we foster a confident environment. Our approach to complaint resolution emphasizes fairness, ensuring that ethical lapses are addressed adequately and that ongoing trust is maintained within the community.

Elimination of Bias and Cultural Competency

We take proactive steps to eliminate bias and promote cultural competency in appraisals. This involves training programs that raise awareness of unconscious biases. We incorporate inclusive practices, reflecting California’s diverse population and ensuring equal treatment in evaluations. Cultural competency strengthens the appraiser-client relationship, promoting fair assessments. By understanding and respecting diverse cultural perspectives, we ensure appraisals are both objective and respectful. Inclusivity is central to maintaining the integrity and relevance of our real estate appraisal services.

Licensing and Professional Development of Appraisers

In the appraisal profession, we focus on creating well-qualified appraisers who adhere to strong professional standards. Licensing, education, and ongoing training are key. The process includes educational courses, hands-on experience, and maintaining a valid appraiser license through regular updates.

Education and Experience Requirements

To become licensed appraisers in California, we must meet specific education and experience requirements. Education usually includes college-level courses and specialized appraisal training. For instance, we need to complete courses in topics like real estate principles and appraisal procedures.

An apprenticeship or work under a certified appraiser provides necessary experience. This practical training helps us apply our knowledge in real-world settings. The Practical Applications of Real Estate Appraisal (PAREA) program is one way we gain this experience. Establishing a strong foundation is crucial before attempting the examination.

National USPAP Course and Update Courses

The National USPAP Course is essential for all appraisers. We must take the 15-hour National USPAP Course to understand uniform standards of professional appraisal practice. It provides the fundamental framework for ethical behavior and competent performance.

To maintain our understanding and comply with changes, we must take the 7-hour National USPAP Update Course every two years. This update keeps us informed about revisions and helps us apply best practices consistently. Regular updates ensure that we stay aligned with national standards and ethical requirements.

Certification and Appraiser License Maintenance

Once certified, it is essential for us to maintain and renew our appraiser licenses. We need to complete continuing education courses, which keep our knowledge current. These courses focus on evolving market trends and changes in laws.

Also, we should adhere to professional standards outlined by state and national boards. Staying compliant involves on-time license renewals and fulfilling required coursework. Keeping our licenses current ensures we maintain credibility in our work and adhere to high ethical standards. Through ongoing learning, we enhance our skills and service quality in the appraisal field.

Appraisal Methodologies and Property Valuation Standards

In examining the landscape of commercial property appraisal, understanding how properties are valued and the standards that guide these valuations is crucial. We engage with valuation approaches, market trends, comparable sales, and the effects of ownership interests and leases.

Approaches to Determining Commercial Property Value

Various methodologies are used to assess commercial property value, each with its unique applications. The cost approach considers the cost of constructing a similar property, minus depreciation. Income capitalization evaluates potential income from the property to determine current value.

Sales comparison uses recent sales of similar properties to estimate value. These methods give us a diverse toolkit to adapt to different market situations.

Analysis of Market Trends and Comparable Sales

Market trends play an essential role in shaping property values. We must keep track of market activity, such as changes in demand or supply dynamics, that can affect prices. This data helps us predict future property value fluctuations.

Comparable sales analysis is another critical aspect. By examining recent transactions of similar properties, we get a sense of the prevailing market rate. This process allows us to anchor our appraisals to real-world scenarios.

Impact of Ownership Interest and Leasing on Valuations

Ownership interests and leasing conditions significantly affect property valuations. When a property is leased, the terms of the lease, including tenant quality and lease duration, can influence its market value.

Ownership variations, such as partial stakes, can also impact appraisals. We need to understand these factors to accurately assess a property’s worth. These elements highlight the complexity of commercial real estate valuations.

Strategies for Success in the California Commercial Real Estate Appraiser Examination: Expert Tips and Techniques

Understanding the Path to California Commercial Appraiser Certification

A person studying at a desk with books, notes, and a laptop surrounded by charts, graphs, and diagrams related to commercial real estate appraisal

To become a commercial real estate appraiser in California, we must navigate specific education paths, understand the USPAP guidelines, and gain necessary experience. Each aspect is crucial for earning certification. Let’s explore these essential elements.

Qualification Pathways and Education Requirements

Aspiring appraisers have several qualification pathways. First, we can start as a trainee under a supervisory appraiser. Our journey involves completing particular qualifying education courses sanctioned by the California Bureau of Real Estate Appraisers (BREA).

Different levels, such as Licensed Residential Appraiser or Certified Residential Appraiser, need unique educational backgrounds and credit hours. For instance, Certified General Appraisers require a bachelor’s degree or 300 course hours. This structured education ensures competence and proficiency in assessing diverse properties.

Comprehending USPAP and Its Importance for Appraisers

We must understand the Uniform Standards of Professional Appraisal Practice (USPAP). This set of guidelines outlines ethical obligations and performance standards that appraisers follow. Keeping up-to-date with these is essential.

USPAP courses are part of the qualifying education and regular training programs. By adhering to these standards, we ensure credible and consistent appraisals. Learning these principles helps us uphold the trust and integrity needed in our profession.

Experience Hours and Supervisory Appraiser Relationships

Gaining experience hours under a supervisory appraiser is vital. This mentorship is essential as it aids our practical learning. We acquire hands-on experience, building the skills required to handle real-world appraisal challenges.

The experience hours required vary. For instance, a Licensed Residential Appraiser requires 1,000 hours, while a Certified General Appraiser needs 3,000 hours over 18 months. Building a solid relationship with a supervisory appraiser enhances our learning journey, providing valuable guidance and insight.

By following these steps, we steadily move toward achieving certification as commercial real estate appraisers in California.

Preparing for the Certification Examination

A person studying at a desk with books, notes, and a laptop open, surrounded by charts and graphs related to commercial real estate appraisal

Our journey to becoming certified appraisers involves careful preparation and smart study techniques. We need to understand the exam’s format, focus on key appraisal concepts, and pick effective training programs to support our learning.

Study Strategies for Mastering Appraisal Concepts

We should create a clear study plan that covers all necessary topics. Focusing on challenging areas will help us improve. It’s important to use flashcards or diagrams to help memorize key terms.

Group study sessions allow us to discuss and solve problems together. We can use these sessions to share knowledge and tackle difficult topics. Mock tests can provide an idea of what to expect, helping us find strengths and weaknesses before the real exam.

Navigating the Exam: Format and Content Overview

Understanding the exam’s format will help us feel more comfortable on test day. Appraiser exams typically combine multiple-choice questions with case studies. We must know the structure and time limits to plan our approach.

We ought to familiarize ourselves with the content areas, such as property valuation and relevant laws. Each section may have different weight, so focusing on what’s most important can guide our study efforts. Knowing what is coming helps reduce anxiety and boost confidence.

Identifying and Utilizing Effective Training Programs

Choosing the right training program is crucial. Several courses specifically target the California appraiser exam. When evaluating programs, we need to check their reputation and success rates of past students.

Online courses can offer flexibility for busy schedules. They allow us to learn at our own pace. On the other hand, in-person workshops provide hands-on experiences and immediate feedback from instructors.

We should also take advantage of professional development seminars or webinars. These can offer insights from experienced appraisers and experts in the field. Leveraging all available resources will ensure we’re well-prepared for the certification exam.

Resources and Study Materials for the California Commercial Real Estate Appraiser Examination: A Comprehensive Guide

Understanding the Appraisal Regulatory Framework

A cluttered desk with open books, study materials, and regulatory documents. A laptop displaying the California Commercial Real Estate Appraiser Examination website

In the realm of California commercial real estate appraisal, it’s essential to grasp the various regulations. These include standards by the Appraiser Qualifications Board, licensing through the Bureau of Real Estate Appraisers, and significant federal and state laws like FIRREA and Title XI.

Role and Standards of the Appraiser Qualifications Board

The Appraiser Qualifications Board (AQB) is a key part of The Appraisal Foundation. It makes sure appraisers maintain high standards by setting education and experience requirements.

These requirements are designed to ensure that real estate appraisers remain competent and professional. Through ongoing learning, or continuing education, appraisers stay up-to-date on techniques and regulations. The AQB also plays a role in the Uniform Standards of Professional Appraisal Practice (USPAP), which sets ethical guidelines and principles that guide us in a consistent and fair valuation process.

Bureau of Real Estate Appraisers Licensing Overview

Our path to becoming a licensed appraiser starts with the Bureau of Real Estate Appraisers (BREA). They regulate and oversee appraiser licensing in California. To gain our license, we need to meet specific education, experience, and examination requirements as set out by BREA.

The bureau ensures that appraisers follow state and federal laws and maintain professional standards. It’s crucial for us to be aware of the licensing process, which includes fulfilling education requirements and passing the necessary exams. Additionally, to maintain our licenses, we must complete continuing education courses that often cover topics like the Elimination of Bias and updated regulations.

Federal and State Appraisal Legislation

Federal and state laws have a significant impact on how we conduct our appraisal work. FIRREA (Financial Institutions Reform, Recovery, and Enforcement Act) plays a major role in regulatory oversight. This law was enacted to improve reliability and accuracy in real estate appraisals.

Title XI of FIRREA mandates the use of standardized appraisal processes for federally related transactions. Both FIRREA and state legislation guide us to comply with Uniform Standards of Professional Appraisal Practice (USPAP), ensuring our work remains accurate, fair, and unbiased. It’s important for us to understand these legislative requirements to provide trustworthy and qualified appraisal services.

Exam Preparation Strategies

Preparing for the California Commercial Real Estate Appraiser Examination requires focus and the right materials. We will explore valuable study materials, dive into valuation methods, and emphasize the importance of practice tests and sample questions.

Study Materials and Course Content

Our approach begins with gathering essential study materials. It’s crucial to have access to up-to-date resources like textbooks, online courses, and prep guides specific to the exam. Many of these resources cover topics required by the education requirements including concepts like the sales comparison, cost, and income approaches.

Opting for a well-structured exam prep course can be highly beneficial. These courses often include detailed explanations, illustrative examples, and calculations to help us understand complex topics. Licensed and certified appraisers often recommend these resources, emphasizing their effectiveness during preparation.

Approaching Different Valuation Methods

Understanding different valuation methods is key to doing well on the exam. The sales comparison approach involves comparing similar properties, while the cost approach estimates how much it would cost to replace or reproduce a property. The income approach calculates a property’s value based on its income potential.

We should aim to master each method by practicing calculations and application scenarios regularly. This will help us gain the needed confidence. Developing cultural competency alongside technical skills ensures we appreciate diverse market dynamics.

Practice Tests and Reviewing Sample Questions

Practice tests are invaluable in preparing for the exam. They mimic the exam format and help us identify areas where we might need extra study. Repeatedly going through sample questions boosts our familiarity with the exam’s structure and types of questions asked.

It’s essential to review our wrong answers on these practice tests, identifying any patterns in mistakes. This helps us improve our understanding and eliminates knowledge gaps before we face the actual exam. Taking time to engage with comprehensive review materials ensures we are thoroughly prepared.

Professional Development and Career Pathways

A desk covered in study materials, textbooks, and resources for the California Commercial Real Estate Appraiser Examination

In the field of real estate appraisal, moving from licensing to certification opens many doors for advancement and specialization. It’s vital to know about further education options, especially if planning to specialize in areas like residential or commercial appraisal. We also need to thoroughly understand the application process to get through it smoothly.

From Licensing to Certification

Beginning as a Licensed Residential Appraiser, we meet specific experience and education requirements. As we advance, the role of Certified Residential Appraiser allows us to assess more complex residential properties. Further experience and additional courses lead us to become Certified General Appraisers, giving us access to a wider range of assignments in both residential and commercial settings.

Certifications improve career prospects and allow us to work on specialized appraisal reports. The Appraisal Institute offers various programs to help us enhance our skills and credentials. Meeting the Appraiser Qualification Criteria ensures we are well-prepared for advanced roles.

Specializations and Continuing Education

Specializations allow us to focus on particular areas of interest, like commercial appraisal or site valuation. We should pursue continuing education through courses and workshops offered by organizations such as the Appraisal Institute. These keep our skills up-to-date and help us stay informed about changes in the real estate market.

Regularly updating our knowledge is crucial for maintaining our appraiser license. The California Bureau of Real Estate Appraisers requires ongoing education to ensure we meet professional standards. It enhances our ability to create more accurate appraisal reports and property descriptions.

Resources for Navigating the Application Process

The application process can be complex, so having access to reliable resources is essential. We can start by visiting the California Bureau of Real Estate Appraisers’ website for information on required documents and steps. Preparing for the exam involves gathering necessary materials and understanding the experience requirements.

Networking with other real estate appraisers is beneficial. They can provide insights and tips for navigating the process. Additionally, using study guides and online platforms helps us prepare better and increases our chances of success. These resources are helpful in achieving our professional goals in the appraisal field.

Common Pitfalls to Avoid in the California Commercial Real Estate Appraiser Examination: Strategies for Success

Understanding the California Commercial Real Estate Appraisal Process

Appraising commercial real estate in California involves several important concepts and methods. These include understanding key valuation approaches, examining market conditions, and recognizing trends affecting property values.

Key Concepts in Commercial Appraisals

In commercial real estate appraisals, we focus on estimating the market value of commercial properties. Market value represents what a property would likely sell for under typical conditions. To determine this, we consider various factors.

For example, assessing property characteristics—such as size, location, and condition—helps shape our view of its value. Commercial properties differ from residential ones, often requiring a deeper look into financial metrics like income potential. We aim to ensure every major element impacting value is taken into account.

Valuation Approaches and Methodologies

The valuation process employs three main approaches: sales comparison, cost, and income approach.

In the sales comparison approach, we analyze recent sales of similar properties. This provides a benchmark for valuing the subject property.

The cost approach estimates value based on the cost to replace or reproduce the property, minus depreciation. It’s particularly useful for newer properties.

Lastly, the income approach evaluates a property’s value through its potential income, making it essential for commercial properties that generate revenue.

Assessment of Market Conditions and Trends

Current market trends play a critical role in appraisals. We monitor local market conditions to understand pricing dynamics. Factors such as supply and demand, interest rates, and economic indicators directly influence property values.

Understanding these elements helps us predict how market shifts might affect property prices. By keeping an eye on market conditions, we provide more accurate valuations for our clients. Market trends, alongside recent sales data, guide our assumptions and projections.

Through in-depth analysis, we gain a clearer picture of the commercial real estate landscape in California.

Commercial Appraisal Reporting and Compliance

In the realm of commercial property appraisal, it’s crucial for us to produce clear, accurate, and compliant reports. This involves preparing thorough appraisal reports and strictly adhering to legal and ethical standards.

Preparing Comprehensive Appraisal Reports

Our appraisal reports must be comprehensive and reliable. Each report should cover all necessary details, such as property descriptions, zoning laws, and property conditions. Accuracy is vital to ensure reliable valuations.

We must review property data meticulously to maintain precision. Attention to zoning regulations and market analysis also helps to present a clear picture. Including proper documentation can strengthen the trustworthiness of our reports and support our valuation conclusions.

Adhering to Legal and Ethical Standards

Ethical compliance is essential. We are bound to follow confidentiality rules, ensuring that no unauthorized information is shared. Our reports should meet all legal standards, staying up-to-date with current laws and regulations.

We should avoid conflicts of interest to maintain integrity. Conducting a due diligence process helps us adhere to these guidelines. We must always strive to present facts clearly and without bias, maintaining fairness in our evaluations.

Financial Considerations in Commercial Appraisal

When appraising commercial properties, we must carefully analyze financial components. These elements play a significant role in property value and can directly impact appraisers’ assessments.

Influence of Financing on Property Valuation

Financing shapes commercial property valuation. Commercial real estate loans affect both the buyer’s and seller’s decisions. Interest rates are a prime factor. When rates rise, the cost of borrowing increases, possibly lowering the property’s market value.

We should consider what financial institutions require. Banks often have strict lending criteria. These can limit potential buyers, thus influencing the property’s perceived value. Understanding loan structures, whether fixed or variable, also impacts appraisal outcomes.

Financing also involves assessing the property’s income potential. Properties with stable income provide better security to lenders. This can make the property more appealing, positively impacting its value. By thoroughly analyzing these factors, we ensure accurate valuations.

Taxation and Insurance Implications

Tax assessments and insurance are crucial in real estate appraisals. Taxes affect net operating income. High property taxes can lead to reduced profitability, lowering market value. We need to analyze local tax rates and potential changes to predict financial outcomes for buyers and sellers.

Insurance plays a vital role too. Lenders require adequate coverage to protect their investments. High insurance costs can be a financial burden, again influencing property value. It’s essential to evaluate both regular premiums and any additional coverage needs.

Investment decisions rest heavily on these evaluations. By understanding tax and insurance obligations, we provide a more comprehensive analysis for accurate commercial property assessments.

Importance of Compliance with Testing Procedures for California Commercial Real Estate Appraisers: Ensuring Accurate Valuations

Understanding Appraisal Standards and Regulations

In California, commercial real estate appraisers must adhere to a set of rigorous standards and regulations. They need proper licensing, must comply with federal and state laws, and participate in ongoing education.

Appraiser Licensing and Qualifications

Appraisers in California need a license issued by the Bureau of Real Estate Appraisers (BREA). Through the California Code of Regulations, the licensing requirements include specific education and experience levels. To qualify, we must meet criteria set by the Appraiser Qualifications Board, such as completion of the 15-hour National USPAP course.

Applicants typically follow the supervisor/trainee model to gain practical experience. It combines field practice and structured education. Appraisers aiming for higher certifications need advanced courses and more extensive appraisal experience.

Federal and State Compliance for Appraisers

Appraisers must align with Title XI of the Financial Institutions Reform, Recovery, and Enforcement Act (FIRREA). This governs their work at the federal level. We must also comply with USPAP standards, which ensure consistent and ethical practices.

State laws, like the California Code of Regulations, outline local requirements. These include adherence to the USPAP guidelines and additional state-specific rules. Local compliance often overlaps with federal standards, making them essential for all practicing appraisers.

Mandatory Education and Continuous Learning

Appraisers must fulfill ongoing education and training requirements to maintain their licenses. Our education includes regular courses like the 7-hour National USPAP Update. This ensures we stay updated on industry standards and legal changes.

Continuous education, or CE, is crucial for professional development. Programs like PAREA offer innovative learning methods. This includes virtual training for appraisers. Our commitment to continuous learning guarantees our competence and adherence to all regulations.

Professional Practice and Ethical Considerations

In the realm of real estate appraisal, maintaining high standards and ethical guidelines is essential. This can impact the accuracy and reliability of real estate appraisers’ work. Complying with professional guidelines and eliminating bias form the backbone of trusted appraisal services.

Adherence to Uniform Standards of Professional Appraisal Practice

All appraisers must follow the Uniform Standards of Professional Appraisal Practice (USPAP). These standards ensure that our appraisal work is consistent and credible. By adhering to USPAP compliance, real estate appraisers in California can provide reliable and accurate property valuations.

Our commitment to these standards helps in maintaining the integrity of our work. Sticking to these guidelines creates uniformity in the appraisal process. It’s essential for us to follow these rules diligently, as they affect the entire real estate market value.

Ethics and Bias Elimination in Appraisal

Eliminating bias is critical in real estate appraisal. We must ensure that our practices are free from any prejudice. This can involve educating ourselves about cultural competency to recognize and counteract potential bias.

Being ethical means ensuring fair appraisals for every client. This not only enhances the trust clients have in our services but also strengthens the overall reputation of our profession. As real estate appraisers, we have a duty to maintain fairness at all times.

Appraisal Methodology and Approaches

In our appraisal practice, we use various methodologies, such as the income approach, sales comparison approach, and mass appraisal. Each method serves a specific purpose in determining a property’s market value. An understanding of these approaches helps us provide accurate and reliable appraisals.

Our expertise in these appraisal methodologies ensures that we select the most appropriate one for each property. This careful selection and application is necessary to deliver the best possible assessment. Applying diverse techniques allows us to address different scenarios in real estate valuation effectively.

Operational and Transactional Guidelines

In the appraisal industry, it’s crucial for licensed appraisers to follow specific guidelines in commercial real estate dealings. These include transactions and financing, assessing risks, resolving disputes, and determining values. Doing so helps ensure accuracy and trust in our work.

Commercial Real Estate Transactions and Financing

We must understand the role of appraisals in commercial transactions and financing. Licensed appraisers provide vital property valuations that impact sales, leasing, and refinancing. Our opinion of value must comply with federal regulations and align with market conditions. Property characteristics, location, and use are key factors we consider. Keeping updated on changes in rules and market trends is necessary for accurate appraisals.

Risk Assessment and Dispute Resolution

Risk assessment helps prevent errors that can lead to costly disputes. We need to identify potential risks early in the appraisal process. This includes checking for zoning issues, environmental concerns, and regulatory compliance. Dispute resolution often involves mediation or arbitration, so it’s important to have comprehensive documentation. By maintaining clear communication and robust reports, we can minimize conflicts and ensure smoother transactions.

Determining Opinion of Value and Use of Comparables

Formulating an accurate opinion of value requires a strong grasp of comparables. We select properties that are similar in terms of location, size, and condition. The comparable sales method involves analyzing recent transactions in the area. This comparison helps establish a range of possible values. Our analysis must be clear and thorough to support our conclusions. Proper use of data ensures our evaluations are defensible and reliable.